Quick answer
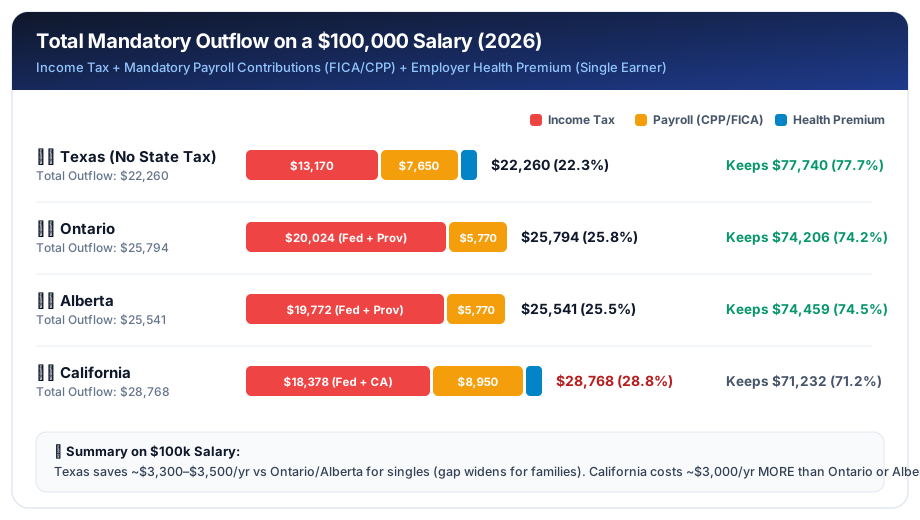
Usually Canada, but not against every state. On a $100,000 salary in 2026, a single earner pays about $20,820 in income tax and payroll contributions in Texas, $25,794 in Ontario, $25,541 in Alberta and $24,643 in British Columbia. In California the same salary costs $27,328.
So against Texas or Florida, Canada costs roughly $4,000–$5,000 a year more at $100,000. Against California or New York it costs about the same or less. The gap widens for high earners: Ontario’s top combined rate is about 53.5% (CRA current-year brackets), against a 37% federal top rate in Texas. It narrows once you count the US health premium you stop paying.
Calculate it: your state vs every province
Enter your salary and current state. The table adds federal, state or provincial income tax, payroll contributions (Social Security and Medicare vs CPP and EI), and the US health premium you stop paying in Canada.
What you pay at each salary (2026)
Income tax plus payroll contributions for one single earner with employment income and only the standard or basic amounts. US: federal, state, Social Security, Medicare (and California SDI). Canada: federal, provincial, CPP/QPP, EI (and QPIP in Quebec). The same number is used on both sides, USD in the US and CAD in Canada, so compare the percentages if you are converting a salary.
| Salary | 🇺🇸 Texas | 🇺🇸 California | 🇺🇸 New York | 🇨🇦 Ontario | 🇨🇦 Alberta | 🇨🇦 B.C. | 🇨🇦 Quebec |
|---|---|---|---|---|---|---|---|
| $50,000 | $7,64515.3% | $9,48819.0% | $9,79019.6% | $9,85519.7% | $9,45918.9% | $9,44218.9% | $10,97121.9% |
| $75,000 | $13,40817.9% | $17,31023.1% | $16,92822.6% | $18,07424.1% | $17,63823.5% | $17,30523.1% | $20,70127.6% |
| $100,000 | $20,82020.8% | $27,32827.3% | $25,77225.8% | $25,79425.8% | $25,54125.5% | $24,64324.6% | $30,07830.1% |
| $150,000 | $36,20924.1% | $48,01732.0% | $44,16129.4% | $45,68030.5% | $42,54228.4% | $42,63928.4% | $51,91034.6% |
| $250,000 | $66,81826.7% | $89,22635.7% | $80,99632.4% | $93,45437.4% | $83,31433.3% | $86,78934.7% | $101,22540.5% |
Data last updated November 4, 2026. Estimate built from 2026 CRA, provincial and IRS brackets (Rev. Proc. 2025-32). Not a CRA or IRS assessment. Use the calculator above for your own salary and state.
Three things stand out. Texas (and Florida or Washington) is the cheapest column at every salary. Alberta and B.C. come in under California at every salary and under New York from $150,000. Quebec is the most expensive column throughout. At $100,000 a Texan pays about $4,700 less than an Albertan, and that is before the Albertan’s health premium drops to zero.
Federal brackets side by side (2026)
The headline rates look similar. The difference is where they start: Canada’s 29% and 33% bands begin at $181,440 and $258,482, while the US 32%–37% bands for a single filer begin above $256,225. Each rate applies only to income inside its band.
| Rate band | 🇺🇸 US federal (single, taxable income) | 🇨🇦 Canada federal (taxable income) |
|---|---|---|
| Lowest | 10% to $12,400 | 14% to $58,523 |
| 2nd | 12% to $50,400 | 20.5% to $117,045 |
| 3rd | 22% to $105,700 | 26% to $181,440 |
| 4th | 24% to $201,775 | 29% to $258,482 |
| 5th | 32% to $256,225 | 33% above $258,482 |
| Top | 35% to $640,600; 37% above | — |
| Tax-free amount | $16,100 standard deduction | $16,452 basic personal amount (credit) |
On top of that, every province charges income tax, while nine US states (including Texas, Florida, Washington, Nevada and Tennessee) charge none on wages. Two provinces as examples:
| Taxable income (2026) | Ontario provincial rate | Alberta provincial rate |
|---|---|---|
| First band | 5.05% to $53,891 | 8% to $61,200 |
| Next bands | 9.15% / 11.16% / 12.16% | 10% / 12% / 13% / 14% |
| Top band | 13.16% over $220,000 (plus Ontario surtax) | 15% over $370,220 |
Sources: CRA, Current year tax rates and income brackets (2026); CRA rate pages; IRS Rev. Proc. 2025-32. Ontario’s combined top marginal rate is higher than 33% + 13.16% because of the provincial surtax.
Payroll taxes: Social Security and Medicare vs CPP and EI
This is the part that works in Canada’s favour. Canadian payroll contributions stop at a much lower salary, so above about $85,000 they stay flat, while US Social Security runs to $184,500 and Medicare never stops.
| 2026, employee share | 🇺🇸 United States | 🇨🇦 Canada (outside Quebec) |
|---|---|---|
| Pension | Social Security 6.2% up to $184,500 | CPP 5.95% on $3,500–$74,600, plus CPP2 4% on $74,600–$85,000 |
| Health / insurance | Medicare 1.45%, no cap; +0.9% above $200,000 | EI 1.63% up to $68,900 |
| Maximum per year | No maximum (Medicare) | About $5,770 (CPP $4,230 + CPP2 $416 + EI $1,123) |
| At $100,000 | $7,650 | $5,770 |
| At $150,000 | $11,475 | $5,770 |
If you work for a US employer while living in Canada (or the reverse), the US–Canada totalization agreement generally means you pay into one system, not both, and credits from each country can count toward the other’s pension.
Sources: CRA CPP rates and maximums; CRA EI premium rates; SSA contribution and benefit base. Quebec uses QPP (6.4%), a lower EI rate and QPIP.
Is sales tax higher in Canada?
Usually, yes. Canada charges a 5% federal GST everywhere, and most provinces add their own tax, either combined into one HST or charged separately. The US has no federal sales tax, so the rate depends entirely on your state and city.
| 🇨🇦 Province | Total sales tax | 🇺🇸 US comparison | Combined state + local |
|---|---|---|---|
| Alberta (GST only) | 5% | Oregon, Delaware, Montana, New Hampshire | 0% |
| Saskatchewan | 11% | Alaska (local only) | about 1.8% |
| British Columbia, Manitoba | 12% | Texas, New York (typical) | about 8%–8.5% |
| Ontario (HST) | 13% | California (average) | about 8.9% |
| Nova Scotia (HST) | 14% | Tennessee | about 9.6% |
| Quebec (GST + QST) | 14.975% | Louisiana (highest) | about 10.1% |
| New Brunswick, Newfoundland and Labrador, P.E.I. (HST) | 15% |
Groceries, prescription drugs and most rent are zero-rated or exempt in Canada, so the gap on a normal household budget is smaller than the rates suggest. Low- and middle-income households also get the quarterly GST/HST credit back.
Sources: CRA GST/HST rates by province (Nova Scotia HST fell to 14% on April 1, 2025); Tax Foundation, State and Local Sales Tax Rates 2026. US combined rates are population-weighted averages.
Capital gains, investments and your house
- Canada: half of a capital gain is added to your income and taxed at your normal rate (50% inclusion). The proposed increase to two-thirds was cancelled in March 2025. There is no separate long-term rate.
- US: gains on assets held over a year are taxed at 0%, 15% or 20%. For a single filer in 2026 the 0% rate applies up to $49,450 of taxable income and 20% starts above $545,500. A 3.8% Net Investment Income Tax applies above $200,000. Short-term gains are ordinary income.
- Your home: Canada’s principal residence exemption can make the whole gain tax-free. The US only excludes $250,000 ($500,000 married). A US citizen who sells a Canadian home can still owe US tax on the gain above that, even if Canada charges nothing.
- When you die or leave: Canada has no estate tax but treats your assets as sold at death (and when you emigrate), so gains are taxed then. The US has an estate tax, with a $15 million exemption in 2026.
Sources: CRA line 12700 capital gains; IRS Topic 409; Rev. Proc. 2025-32.
TFSA, RRSP and 401(k): the US citizen trap
Canada’s registered accounts don’t all work for Americans:
- RRSP (2026 limit: 18% of last year’s earned income, up to $33,810): safe. The tax treaty lets the growth stay tax-deferred on your US return too, and since Rev. Proc. 2014-55 the deferral is automatic.
- TFSA (2026 limit: $7,000) and FHSA ($8,000/year, $40,000 lifetime): tax-free in Canada, but neither is covered by the Canada–US tax treaty. Interest, dividends and gains inside them are taxable on your US Form 1040, and some advisers treat a TFSA as a foreign trust requiring Form 3520/3520-A. Many cross-border planners tell US citizens to skip both.
- RESP (education savings, 20% federal match up to $500/year): IRS Rev. Proc. 2020-17 exempts eligible US citizens from Form 3520/3520-A foreign-trust filings on Canadian RESPs, but internal earnings and government grants remain reportable on your US return (if one parent is not a US person, families often make that parent the sole subscriber).
- Canadian mutual funds and ETFs: for a US person these are usually PFICs (Form 8621), which are taxed harshly. Individual stocks, or US-listed ETFs held through a cross-border broker or inside an RRSP, avoid that.
- Your 401(k) and IRA: they can generally stay invested and tax-deferred after you move, under Article XVIII of the treaty. Get advice before cashing out or moving money to an RRSP. Full rules, including the Roth IRA election: 401(k), IRA and RRSP for Americans moving to Canada.
Sources: CRA TFSA contributions; CRA RRSP deduction limit.
Do Americans in Canada owe US tax?
You still file a US return every year, because the United States taxes citizens wherever they live. Most Americans in Canada end up owing the IRS little or nothing, because Canadian tax on the same income is usually higher:
- Foreign Tax Credit (Form 1116): credits Canadian income tax against US tax on the same income. This is usually the better choice in Canada, and unused credits carry forward.
- Foreign Earned Income Exclusion (Form 2555): excludes up to $132,900 of 2026 wages. It is less useful in a high-tax country and can block refundable credits.
- Treaty: the Canada–United States tax treaty decides which country taxes pensions, Social Security and investment income first.
- Account reporting: FinCEN Form 114 (FBAR) if your Canadian accounts together exceed $10,000 USD at any time in the year, and Form 8938 above $200,000 at year-end or $300,000 at any time for a single filer living abroad.
- Canadian foreign-asset form: if your US bank and brokerage accounts and other foreign investments cost more than $100,000 CAD in total at any time in the year, file CRA Form T1135. You do not file it for the year you first become resident. The Budget 2026 tax measures (November 5, 2026) propose raising that threshold to $200,000 for tax years ending after 2026.
- Deadlines: Canada’s return is due April 30 (June 15 if you or your spouse are self-employed, with any balance still due April 30). Budget 2026 proposes moving the filing and payment date to May 15 for everyone, starting with 2027 returns filed in 2028. The US deadline is April 15, with an automatic extension to June 15 if you live abroad (interest still runs from April 15).
- Your old state: some states keep treating you as a resident until you clearly cut ties. Close or move your driver’s licence, voter registration and in-state address.
Should I use the foreign earned income exclusion or the foreign tax credit?
Filing in both countries does not mean the same wages are fully taxed twice. For 2026, Form 2555 can exclude up to $132,900 of foreign earned income, which is pay for work you did abroad, not pensions, interest or capital gains. That choice stays in effect until you revoke it, and after a revocation the IRS will not let you claim the exclusion for the next 5 tax years unless it approves. You also cannot claim a foreign tax credit on the dollars you excluded. The credit, Form 1116, is the other tool, and it is usually the better fit where Canadian income tax is higher. Do not revoke an exclusion you have already claimed without a cross-border tax professional. See the IRS guide to figuring the exclusion.
Does the CPP line on my T4 count as a US foreign tax credit?
No. CPP or QPP on a T4 is a pension contribution, not the income tax you claim on Form 1116. IRS Publication 514 says you cannot take a credit or a deduction for social security taxes paid to a country that has a social security agreement with the United States, and Canada has one. Self-employment is separate. The Social Security Administration says a self-employed person living in Canada is covered by the Canada or Quebec pension system and should attach a certificate of coverage to the US return. Ask the CRA whether it will issue form CPT56, or Retraite Québec for the Quebec plan, before you leave US self-employment tax off a return. A cross-border tax professional should check that certificate against your facts.
I never filed from Canada. Does my RRSP go on Form 8938?
A Canadian RRSP is not left off the foreign-account report. The IRS manual (IRM 4.26.16) says an RRSP is normally reportable on the FBAR once foreign accounts pass $10,000 USD at any point in the year. Form 8938 is a second form, and filing one does not replace the other. Abroad, it starts above $200,000 at year-end or $300,000 at any time if you file alone, and double that on a joint return. The Streamlined Foreign Offshore Procedures are only for a non-willful miss: the last 3 tax years, the last 6 FBAR years, the tax and interest, and Form 14653. You must also have spent at least 330 full days outside the United States in one of those three years. A willful failure is outside this path, and the domestic version charges a 5 percent penalty. Talk to a cross-border tax professional before you file.
Use a US/Canada cross-border accountant for your first year. The move year has two part-year returns in each country and is where most mistakes happen.
Taxes plus health care and childcare: two households
Taxes are only part of the comparison. These two examples add back the main costs that Canadian taxes cover.
Family of four, one earner at $120,000: Texas vs Alberta
| Cost | 🇺🇸 Texas | 🇨🇦 Alberta |
|---|---|---|
| Income tax + payroll (married, one earner) | $19,220 | $27,618 |
| Health premium, worker share (KFF family average) | $6,850 | $0 |
| Deductible and copays (KFF average deductible; Alberta: drugs and dental not covered by employer) | $1,886 | $400 |
| Full-time daycare, two children under 5 | $22,000 | $7,830 |
| Total | $49,956 | $35,848 |
| Left from $120,000 | $70,044 | $84,152 |
Illustrative, not a CRA or IRS calculation; same number on both sides with no currency conversion. Tax from the calculator above. Alberta daycare uses the provincial flat parent fee of $326.25/month per full-time child; Texas assumes about $11,000 per child for centre care, which varies a lot by city. The Canada Child Benefit would add more on the Alberta side. Quebec’s 2026 reduced-contribution daycare rate is $9.65/day.
Single tech worker at $180,000: California vs Ontario
| Cost | 🇺🇸 California | 🇨🇦 Ontario |
|---|---|---|
| Income tax | $44,582 | $53,384 |
| Payroll (Social Security, Medicare, SDI vs CPP, EI) | $16,110 | $5,770 |
| Health premium + deductible (KFF single averages) | $3,326 | $200 |
| Total | $64,018 | $59,354 |
Ontario charges about $8,800 more in income tax, but California payroll is about $10,300 higher because Social Security runs to $184,500 and SDI has no cap. The difference is salary: the same tech job often pays more in California than in Toronto.
What Canadian taxes pay for
Hospital and doctor care
Doctor visits, emergency rooms, surgeries, hospital stays and MRIs are covered by your provincial plan, with no premiums or deductibles. Most provinces cover you from day one; a few have a waiting period after you arrive.
Parental leave
Canada pays Employment Insurance parental benefits. Standard parental is 55% of average insurable weekly earnings for up to 40 weeks shared (2026 weekly max $729); extended is 33% for up to 69 weeks (weekly max $437). See Service Canada EI maternity and parental benefits. The US has no federal paid parental-leave mandate.
Cheaper childcare
Quebec’s official 2026 reduced-contribution rate is $9.65 per day at subsidized centres. Other provinces have cut fees under the Canada-Wide Early Learning and Child Care plan, but spaces are limited, so check your province rather than assuming $10/day everywhere.
Canada Child Benefit
Tax-free monthly payments. For July 2026–June 2027 the maximum is $679.75/month per child under 6 and $573.58/month per child aged 6–17, reduced once adjusted family net income exceeds $38,237 (CRA CCB amounts).
Lower university tuition
Domestic undergraduate tuition is set by provinces and is generally far below US private-university sticker prices. Check Statistics Canada Table 37-10-0045-01 for the current year.
Lower drug prices
Patented drug prices are federally regulated. A month of insulin that costs $300+ USD at US list price typically costs $30–$60 CAD in Canada. Prescriptions are not covered by the public plan for most working-age adults, so you still need employer or private drug coverage.
Who comes out ahead?
- Single, high income, from a no-tax state: the US wins clearly. At $250,000 a Texan pays about $66,800 in tax and payroll; an Ontarian about $93,500 and an Albertan about $83,300.
- Middle income from California or New York: close to even on tax, and Canada usually wins once health premiums are included.
- Families with young children: Canada often wins because of subsidized daycare, the Canada Child Benefit and no family health premium, even from Texas.
- Investors and retirees: it depends on the details. Watch the TFSA and PFIC rules, the home-sale exclusion and the deemed sale when you leave Canada.
Frequently asked questions
See your after-tax numbers by province
The province calculator adds rent, groceries, healthcare and childcare to your tax bill and shows your real monthly take-home.